

[Feb-2022] Use Real 8008 Dumps Free Sample Questions and Practice Test Engine
Pass PRMIA 8008 exam - questions - convert Tets Engine to PDF
NEW QUESTION 156
What would be the consequences of a model of economic risk capital calculation that weighs all loans equally regardless of the credit rating of the counterparty?
I. Create an incentive to lend to the riskiest borrowers
II. Create an incentive to lend to the safest borrowers
III. Overstate economic capital requirements
IV. Understate economic capital requirements
- A. III only
- B. II and III
- C. I and IV
- D. I only
Answer: C
Explanation:
Explanation
If capital calculations are done in a standard way regardless of risk (as reflected by credit ratings), then it creates a perverse incentive for the lenders' employees to lend to the riskiest borrowers that offer the highest expected returns as there is no incentive to 'save' on economic capital requirements that are equal for both safe and unsafe borrowers. Therefore statement I is correct.
Given that the portfolio of such an institution is likely to then comprise poor quality borrowers, and economic capital would be based upon 'average' expected ratings, it is likely to carry lower economic capital given its exposures. Therefore any such economic risk capital model is likely to understate economic capital requirements. Therefore statement IV is correct.
Statements II and III are incorrect and Choice 'b' is the correct answer.
NEW QUESTION 157
There are two bonds in a portfolio, each with a market value of $50m. The probability of default of the two bonds are 0.03 and 0.08 respectively, over a one year horizon. If the probability of the two bonds defaulting simultaneously is 1.4%, what is the default correlation between the two?
- A. 40%
- B. 0%
- C. 100%
- D. 25%
Answer: D
Explanation:
Explanation
Probability of the joint default of both A and B =
We know all the numbers except default correlation, and we can solve for it.
Default Correlation*SQRT(0.03*(1 - 0.03)*0.08*(1 - 0.08)) + 0.03*0.08 = 0.014.
Solving, we get default correlation = 25%
NEW QUESTION 158
A risk analyst uses the GARCH model to forecast volatility, and the parameters he uses are = 0.001%, = 0.05 and = 0.93. Yesterday's daily volatility was calculated to be 1%. What is the long term annual volatility under the analyst's model?
- A. 0.22 %
- B. 3.54 %
- C. 0.25 %
- D. 7.94 %
Answer: B
Explanation:
Explanation
The correct answer is choice 'a'
Recall the following summary of the GARCH model. The long term variance in a GARCH model is given by
/(1 - - ). In this case, this works out to =SQRT(0.001/(1 - 0.05 - 0.93)) * SQRT(250) = 3.54%. Yesterday's volatility of 1% is irrelevant to the question.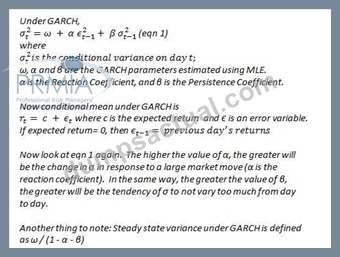
NEW QUESTION 159
Which of the following is not a measure of risk sensitivity of some kind?
- A. Convexity
- B. CR01
- C. Delta
- D. PL01
Answer: D
Explanation:
Explanation
Measures of risk sensitivity include delta, gamma, vega, PV01, convexity and CR01, among others. They allow approximating the change in the value of a portfolio from a change (generally small) in one of the underlying risk factors.
Risk sensitivity measures are derivatives of the value of the portfolio, calculated with respect to the risk factor.
Some risk sensitivity measures are second derivatives, and allow a more precise calculation of the change in the value of the portfolio. Many risk sensitivities are represented by Greek letter, but not all.
Delta () is a measure of the change in portfolio value based on a 1% change in the value of the underlying.
Gamma () is a second order derivative that improves the calculation as part of a Taylor expansion. CR01 is a measure of the change due to a 1 basis point change in the credit spread. PL01 is not a measure of any kind of risk sensitivity, it does not mean anything.
NEW QUESTION 160
A derivative contract has a negative current replacement value. Which of the following statements is true about its loan equivalent value for credit risk calculations over a 2-year horizon?
- A. Since the derivatives contract has a negative current replacement value, exposure will be zero.
- B. The credit exposure will be a given quintile of the expected distribution of the value of the derivatives contract in the future.
- C. The current exposure can be used for loan equivalence calculations as that is an unbiased proxy for the future value.
- D. The notional value of the derivatives contract should be used for loan equivalence calculations.
Answer: B
Explanation:
Explanation
The current exposure is negative, so there is no immediate credit exposure. However, since the price of the derivative is volatile, we can reasonably expect the value to be greater than zero sometime in the future. This is a stochastic variable which will have a distribution, and not just a unique value, in the future that will represent the credit exposure. Since there is no unique value, a conservative approach is to pick a quintile of the distribution, and use that as the future value of the derivative contract, with the assurance that the probability of the credit exposure exceeding that quintile is known and has been consciously selected. This number can then be converted to a loan equivalent amount for credit risk purposes. Therefore Choice 'b' is the correct answer. Choice 'a', Choice 'd' and Choice 'c' are incorrect for these reasons.
NEW QUESTION 161
Which of the following is the most important problem to solve for fitting a severity distribution for operational risk capital:
- A. The fit obtained should reduce the combination of the fitting and approximation errors to a minimum
- B. Determine plausible scenarios to fill the data gaps in the internal and external loss data
- C. Empirical loss data needs to be extended to the ranges below the reporting threshold and above large value losses
- D. The risk functional's minimization should lead to a good estimate of the 0.999 quantile
Answer: D
Explanation:
Explanation
Ultimately, the objective of the operational risk severity estimation exercise is to calculate the 99.9th percentile loss over a one year horizon; and everything else we do with data, collecting loss information, modeling, curve fitting etc revolves around this objective. If we cannot estimate the 99.9th percentile loss accurately, then not much else matters. Therefore Choice 'a' is the correct answer.
Minimizing the combination of fitting and approximation errors is one of the things we do with a view to better estimating the operational loss distribution. Likewise, empirical loss data generally is range bound because corporations do not require employees to log losses less than an threshold, and high value losses are generally rare. This problem is addressed by extrapolating both large and small losses, something that impacts the performance of our model. Likewise, one of the objectives of scenario analysis is to fill data gaps by generating plausible scenarios. Yet while all these are real issues to address, the primary problem we are trying to solve is estimating the 0.999th quantile.
NEW QUESTION 162
Calculate the 99% 1-day Value at Risk of a portfolio worth $10m with expected returns of 10% annually and volatility of 20%.
- A. 0
- B. 1
- C. 2
- D. 3
Answer: A
Explanation:
Explanation
Be wary of questions asking you to calculate VaR where the mean or expected returns are different from zero.
The VaR formula of z-value times standard deviation needs to have an adjustment for the expected return [ie use VaR = z-value times standard deviation minus expected return]. In this case, the standard deviation for 1 day for the portfolio is =SQRT(1/250)*20%*$10m = $126,491. The VaR is therefore (2.326 * $126,491) - ($10,000,000 * 10% * 1/250) = $290,218.
NEW QUESTION 163
If the duration of a bond yielding 10% is 6 years, the volatility of the underlying interest rates 5% per annum, what is the 10-day VaR at 99% confidence of a bond position comprising just this bond with a value of $10m?
Assume there are 250 days in a year.
- A. 0
- B. 1
- C. 2
- D. 3
Answer: D
NEW QUESTION 164
If two bonds with identical credit ratings, coupon and maturity but from different issuers trade at different spreads to treasury rates, which of the following is a possible explanation:
I. The bonds differ in liquidity
II. Events have happened that have changed investor perceptions but these are not yet reflected in the ratings III. The bonds carry different market risk IV. The bonds differ in their convexity
- A. I, II and IV
- B. I and II
- C. II and IV
- D. III and IV
Answer: B
Explanation:
Explanation
When two bonds that appear identical in every respect trade at different prices, the difference is often due to differences in liquidity between the two bonds (the less liquid bond will be cheaper and yield higher), and also due to the fact that ratings from the major rating agencies do not generally react to day to day changes in the market. The market's perception of the differences in the two credits will cause a divergence in the prices. This has been an extremely visible phenomenon during the credit crisis of 2007-2009, where fixed income security prices have changed sharply for many securities without any changes in external credit ratings.
Bonds carrying 'different market risk' is meaningless, and so is the difference in convexity (because the calculated convexity would be identical for similar bonds).
Therefore Choice 'c' is the correct answer.
NEW QUESTION 165
The standalone economic capital estimates for the three uncorrelated business units of a bank are $100, $200 and $150 respectively. What is the combined economic capital for the bank?
- A. 0
- B. 1
- C. 2
- D. 3
Answer: B
Explanation:
Explanation
Since the business units are uncorrelated, we can get the combined EC as equal to the square root of the sum of the squares of the individual EC estimates. Therefore Choice 'a' is the correct answer.
[=SQRT(100^2+200^2+150^2)]
NEW QUESTION 166
The estimate of historical VaR at 99% confidence based on a set of data with 100 observations will end up being:
- A. the worst single observation in the data set
- B. the weighted average of the top 2.33 observations
- C. None of the above
- D. the extrapolated returns of the last 1.64 observations
Answer: A
Explanation:
Explanation
The VaR in this case will be the top quintile of observations. In this case, since there are exactly 100 observations, this would mean the worst return would become the VaR. Therefore Choice 'b' is the correct answer. Choice 'a' and Choice 'c' make no sense. This highlights that at higher confidence levels, fewer and fewer observations impact the VaR if we are using historical simulation based VaR.
NEW QUESTION 167
Which of the following belong to the family of generalized extreme value distributions:
I. Frechet
II. Gumbel
III. Weibull
IV. Exponential
- A. II and III
- B. I, II and III
- C. All of the above
- D. IV
Answer: B
Explanation:
Explanation
Extreme value theory focuses on the extreme and rare events, and in the case of VaR calculations, it is focused on the right tail of the loss distribution. In very simple and non-technical terms, EVT says the following:
1. Pull a number of large iid random samples from the population,
2. For each sample, find the maximum,
3. Then the distribution of these maximum values will follow a Generalized Extreme Value distribution.
(In some ways, it is parallel to the central limit theorem which says that the the mean of a large number of random samples pulled from any population follows a normal distribution, regardless of the distribution of the underlying population.) Generalized Extreme Value (GEV) distributions have three parameters: (shape parameter), (location parameter) and (scale parameter). Based upon the value of , a GEV distribution may either be a Frechet, Weibull or a Gumbel. These are the only three types of extreme value distributions.
NEW QUESTION 168
When fitting a distribution in excess of a threshold as part of the body-tail distribution method described by the equation below, how is the parameter 'p' calculated.
Here, F(x) is the severity distribution. F(Tail) and F(Body) are the parametric distributions selected for the tail and the body, and T is the threshold in excess of which the tail is considered to begin.
- A. If there are N observations, of which K are up to T, then p = k/N
- B. If there are K observations up to the tail threshold, then p = k*n
- C. p is a parameter estimated using either the sum of least squares or maximum likelihood estimation
- D. p is a function of the reporting threshold and determined by the log-likelihood functional
Answer: A
Explanation:
Explanation
p = k/N. If there are N observations of which K are upto T, then p = k/N allows us to have a continuous unbroken curve which gets increasingly weighted towards the distribution selected for the tail as we move towards the 'right', ie the higher values of losses.
The other choices are incorrect and mostly nonsensical.
NEW QUESTION 169
Which of the following is not an approach proposed by the Basel II framework to compute operational risk capital?
- A. Advanced measurement approach
- B. Factor based approach
- C. Standardized approach
- D. Basic indicator approach
Answer: B
Explanation:
Explanation
Basel II proposes three approaches to compute operational risk capital - the basic indicator approach (BIA), the standardized approach (SIA) and the advanced measurement approach (AMA). There is no operational risk approach called the factor based approach.
NEW QUESTION 170
If the cumulative default probabilities of default for years 1 and 2 for a portfolio of credit risky assets is 5% and 15% respectively, what is the marginal probability of default in year 2 alone?
- A. 10.53%
- B. 10.00%
- C. 15.79%
- D. 11.76%
Answer: A
Explanation:
Explanation
One way to think about this question is this: we are provided with two pieces of information: if the portfolio is worth $100 to start with, it will be worth $95 at the end of year 1 and $85 at the end of year 2. What it is asking for is the probability of default in year 2, for the debts that have survived year 1. This probability is
$10/$95 = 10.53%. Choice 'b' is the correct answer.
Note that marginal probabilities of default are the probabilities for default for a given period, conditional on survival till the end of the previous period. Cumulative probabilities of default are probabilities of default by a point in time, regardless of when the default occurs. If the marginal probabilities of default for periods 1, 2... n are p1, p2...pn, then cumulative probability of default can be calculated as Cn = 1 - (1 - p1)(1-p2)...(1-pn). For this question, we can calculate the probability of default for year 2 as [1 - (1 - 5%)(1 - 10.53%)] = 15%.
NEW QUESTION 171
Which of the following statements is true:
I. Confidence levels for economic capital calculations are driven by desired credit ratings II. Loss distributions for operational risk are affected more by the severity distribution than the frequency distribution III. The Advanced Measurement Approach (AMA) referred to in the Basel II standard is a type of a Loss Distribution Approach (LDA) IV. The loss distribution for operational risk under the LDA (Loss Distribution Approach) is estimated by separately estimating the frequency and severity distributions.
- A. I and II
- B. III and IV
- C. I, II and IV
- D. I, III and IV
Answer: C
Explanation:
Explanation
Statement I is correct. Economic capital is the capital available to absorb unexpected losses, and credit ratings are also based upon a certain probability of default. Economic capital is often calculated at a level equal to the confidence required for the desired credit rating. For example, if the probability of default for a AA rating is
0.02%, then economic capital maintained at a 99.98% would allow for such a rating. Economic capital set at a
99.8% level can be thought of as the level of losses that would not be exceeded with a 99.8% probability.
Loss distributions are the product of the severity and frequency distributions, each of which are estimated separately. The total loss distribution is affected far more by the severity distribution than by the frequency distribution, therefore statement II is correct.
The Loss Distribution Approach (LDA) is one of the ways in which the requirements of the AMA can be satisfied, and not the other way round. Therefore statement III is incorrect.
Statement IV is correct as the total loss distribution is estimated using separate estimates of loss frequency and distributions.
NEW QUESTION 172
When compared to a low severity high frequency risk, the operational risk capital requirement for a medium severity medium frequency risk is likely to be:
- A. Lower
- B. Unaffected by differences in frequency or severity
- C. Zero
- D. Higher
Answer: D
Explanation:
Explanation
High frequency and low severity risks, for example the risks of fraud losses for a credit card issuer, may have high expected losses, but low unexpected losses. In other words, we can generally expect these losses to stay within a small expected and known range. The capital requirement will be the worst case losses at a given confidence level less expected losses, and in such cases this can be expected to be low.
On the other hand, medium severity medium frequency risks, such as the risks of unexpected legal claims,
'fat-finger' trading errors, will have low expected losses but a high level of unexpected losses. Thus the capital requirement for such risks will be high.
It is also worthwhile mentioning high severity and low frequency risks - for example a rogue trader circumventing all controls and bringing the bank down, or a terrorist strike or natural disaster creating other losses - will probably have zero expected losses & high unexpected losses but only at very high levels of confidence. In other words, operational risk capital is unlikely to provide for such events and these would lie in the part of the tail that is not covered by most levels of confidence when calculating operational risk capital.
Note that risk capital is required for only unexpected losses as expected losses are to be borne by P&L reserves. Therefore the operational risk capital requirements for a low severity high frequency risk is likely to be low when compared to other risks that are lower frequency but higher severity.
Thus Choice 'c' is the correct answer.
NEW QUESTION 173
Which of the following assumptions underlie the 'square root of time' rule used for computing VaR estimates over different time horizons?
I. the portfolio is static from day to day
II. asset returns are independent and identically distributed (i.i.d.)
III. volatility is constant over time
IV. no serial correlation in the forward projection of volatility
V. negative serial correlations exist in the time series of returns
VI. returns data display volatility clustering
- A. I and II
- B. I, II, V and VI
- C. I, II, III and IV
- D. III, IV, V and VI
Answer: C
Explanation:
Explanation
The square root of time rule can be used to convert, say a 1-day VaR to a 10-day VaR, by multiplying the known number by the square root of time to get the VaR over a different time horizon. However, there are key assumptions that underlie the application of this rule, and statements I to IV correctly state those assumptions.
Statements V and VI are not correct, because the application of the square root of time rule requires the absence of serial correlations, and also the absence of volatility clustering (ie independence). Therefore Choice
'c' is the correct answer.
The square root of time rule is also applied to convert volatility or standard deviation for one period to the volatility for a different time period. Remember that VaR is just a multiple of volatility, and therefore the assumptions that apply to the square root of time rule for VaR also apply to the same rule when used in the context of volatilities or standard deviation.
NEW QUESTION 174
Which of the following formulae describes CVA (Credit Valuation Adjustment)? All acronyms have their usual meanings (LGD=Loss Given Default, ENE=Expected Negative Exposure, EE=Expected Exposure, PD=Probability of Default, EPE=Expected Positive Exposure, PFE=Potential Future Exposure)
- A. LGD * EPE * PD
- B. LGD * ENE * PD
- C. LGD * EE * PD
- D. LGD * PFE * PD
Answer: A
Explanation:
Explanation
The correct definition of CVA is LGD * EPE * PD. All other answers are incorrect.
CVA reflects the adjustment for counterparty default on derivative and other trading book transactions. This reflects the credit charge, that neeeds to be reduced from the expected value of the transaction to determine its true value. It is calculated as a product of the loss given default, the probability of default and the average weighted exposure of future EPEs across the time horizon for the transaction.
The future exposures need to be discounted to the present, and occasionally the equations for CVA will state that explicitly. Similarly, in some more advanced dynamic models the correlation between EPE and PD is also accounted for. The conceptual ideal though remains the same: CVA=LGD*EPE*PD.
NEW QUESTION 175
Once the frequency and severity distributions for loss events have been determined, which of the following is an accurate description of the process to determine a full loss distribution for operational risk?
- A. A firm wide operational risk distribution is generated by adding together the frequency and severity distributions
- B. The frequency distribution alone forms the basis for the loss distribution for operational risk
- C. A firm wide operational risk distribution is set to be equal to the product of the frequency and severity distributions
- D. A firm wide operational risk distribution is generated using Monte Carlo simulations
Answer: D
Explanation:
Explanation
Once the frequency distribution has been determined (for example, using the binomial, Poisson or the negative binomial distributions) and the severity distribution has also been determined (for example, using the lognormal, gamma or other functions), the loss distribution can be produced by a Monte Carlo simulation using successive drawings from each of these two distributions. It is assumed that the severity and frequency are independent of each other. The resulting distribution gives a distribution showing the losses for operational risk, from which there Op Risk VaR can be determined using the appropriate percentile.Therefore Choice 'b' is the correct answer.
NEW QUESTION 176
......
Pass Your 8008 Exam Easily - Real 8008 Practice Dump Updated Feb 12, 2022: https://www.dumpsactual.com/8008-actualtests-dumps.html
